Image Credit: AI Generated
How did the Florida garage fire lead to a compensation dispute
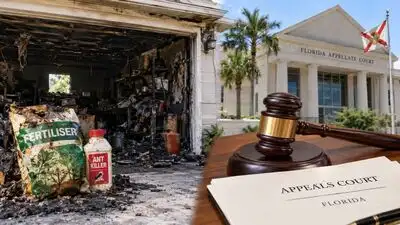
In September 2018, fertiliser and red ant killer stored in a Florida garage spontaneously combusted, causing damage to a home and its contents. Nearly 8 years later, a Florida appeals court overturned decisions that prevented the homeowner from pursuing compensation for his damaged belongings and presenting evidence of the full extent of his losses. Florida Insurance Guaranty Association, the fire occurred at Sam Florio’s home in New Smyrna Beach, Florida, in September 2018. In addition to covering damage to the building and additional living expenses, the policy included up to $159,000 in cover for personal belongings. The insurer paid a combined $54,800.66 to Florio and Servpro, but the parties could not agree on the total value of the losses. Florio filed a breach of contract lawsuit against Southern Fidelity in February 2019. In its ruling dated 2 October 2026, it concluded that Florio had presented enough evidence for his personal property claim to proceed. A second issue concerned FIGA’s statutory limit of $500,000.
Because the evidence is considered legally insufficient, a directed verdict is a decision made by a judge to resolve a claim without allowing the jury to decide it. Because he had paid extra for replacement-cost coverage, he was not required to establish the depreciated value of every damaged item in the same way as a policyholder insured only for actual cash value. Because the full value of a loss and the amount legally recoverable from FIGA are not necessarily the same, this distinction matters.
As reported by Insurance Business, the disagreement eventually became a legal battle over the evidence needed to support his claim. As reported on LAWS website in its coverage of the dispute, FIGA maintained that the absence of a complete inventory made the claim too uncertain. Insurance Business reported that FIGA had agreed to admit the homeowner’s proposed exhibits before later arguing that the evidence was insufficient.
According to the Florida Fifth District Court of Appeal’s ruling in Sam Florio v. The fact that he lacked a complete professional inventory did not automatically make his evidence inadequate, according to the judgment. What followed was a lengthy insurance dispute that continued even after the homeowner’s insurer became insolvent. The ruling allows the dispute to return to a lower court, where the claim can be considered again. The spontaneous combustion of fertiliser and red ant killer in his garage damaged both the property and its contents. Florio had a home insurance policy with Southern Fidelity Insurance Company. He had also paid an additional premium to insure those belongings at their replacement cost, rather than having depreciation deducted from their value. After the fire, the insurer hired Servpro to carry out restoration work and prepare an inventory of the damaged contents. The insurer accepted that the losses were covered under the policy but disputed their extent and value. The legal proceedings were subsequently paused after Southern Fidelity became insolvent and entered liquidation. The Florida Insurance Guaranty Association, commonly known as FIGA, was then substituted as the defendant. FIGA is a public, non-profit organisation established to help pay eligible insurance claims when covered insurers become insolvent. However, its payments are subject to a statutory limit. The trial court accepted that argument and granted a directed verdict against Florio on his personal property claim, effectively preventing the jury from awarding compensation for those losses. The Fifth District Court of Appeal disagreed with the lower court’s decision. Florio had testified about his belongings, explained what had been damaged and presented photographs and receipts that could help establish the losses. The appeals court found that the association could not simply disregard the consequences of that agreement. The court also considered the significance of the replacement-cost provision in Florio’s insurance policy. The ruling did not establish that Florio was entitled to every amount he claimed. Instead, it determined that his evidence should have been considered rather than having the entire personal property claim dismissed. The trial court granted the request. Florio argued that the limit on the amount he could ultimately recover should not prevent him from showing the full extent of his losses. The appeals court agreed. As explained in the judgment the statutory ceiling limits recovery rather than the amount of evidence a claimant may present. Evidence of damages exceeding the statutory limit can still be relevant even if the final payment remains subject to that ceiling.
However, Florio became dissatisfied with the company’s business practices and dismissed it before the work was completed. Before the trial began, the association had sought to prevent Florio from presenting evidence of total damages exceeding that amount.
The case eventually reached a jury trial in January 2025, according to the court judgment. Florio told the court that he had inventoried approximately 90% of the contents. The court record also explains that Servpro had moved the garage contents into 6 portable storage containers.
He said he had established replacement values for many items using receipts, personal knowledge and his own research. By then, Florio’s lawyer had withdrawn, leaving him to present his case without legal representation. He described the damage caused by the fire, showed photographs of the affected property and produced receipts for items he had replaced. He also maintained records of the work carried out on the house and explained the belongings that had been discarded. These included appliances, a kayak, two all-terrain vehicles, food, spices and clothing. He also presented photographs showing items kept in his freezers, including animals stored for food and taxidermy. The main difficulty was that Florio had not supplied a complete inventory identifying every damaged item and its replacement value. FIGA argued that his evidence was insufficient to establish ownership and prove the amount of his personal property losses. Months later, experts hired by both parties examined the items and concluded that they were all rubbish. The contents were subsequently disposed of. The appeals court reversed the decision dismissing the personal property claim and vacated the order restricting evidence of damages beyond the statutory cap. The case will return to the lower court for further proceedings. Florio will have another opportunity to present evidence supporting his claim for damaged belongings, although the ruling does not guarantee a particular award. You use AI every day. Now get your AI Quotient. Take the AIQ test.