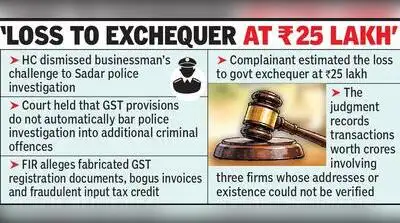
Nagpur: The Nagpur bench of Bombay High Court recently upheld the authority of regular police to investigate alleged GST-related fraud when it also involves offences under general criminal law. It dismissed a businessman’s plea to declare the investigation by Sadar police station illegal.
Wakode ruled that the provisions of the Maharashtra Goods and Services Tax (MGST) Act do not, by themselves, prevent police from investigating offences under the Bharatiya Nyaya Sanhita (BNS), 2023, arising from the same set of facts. The record cited purchases by the petitioner’s firm worth over Rs67 crore in July 2025. The petitioner argued that Sections 132(6) and 134 of the MGST Act restricted prosecution for GST offences, while the statutory framework assigned specific powers to tax officers. The judges also referred to Section 72 of the MGST Act, which requires police and other specified officers to assist tax authorities in implementing the law.
The police investigation revealed transactions involving several entities whose registered addresses could not be traced or whose existence could not be established during verification. A division bench of Justices Urmila Joshi Phalke and Raj. He also relied on judicial precedents to contend that the police lacked authority to independently investigate the matter. Rejecting the argument, the bench relied on Supreme Court rulings which recognised that the existence of a special statute does not automatically displace the regular police’s authority to investigate other criminal offences arising from the same transaction. They noted that the FIR invoked BNS provisions relating to cheating and forgery in addition to offences under the MGST Act.
The court dismissed the criminal writ petition by a Navi Mumbai-based automobile parts trader, who challenged the investigation arising from an FIR on Dec 21, 2025, arguing that the MGST Act assigns specific investigative powers to designated tax authorities. The petitioner had not been named as an accused in the FIR. The court observed that an FIR is not an exhaustive account of a case but the first step in setting the investigative process in motion. Since the investigation was still underway and the petitioner was not an accused in the FIR, it found no ground to quash the proceedings against him.