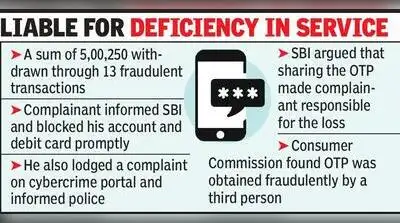
Nagpur: State Bank of India (SBI) Tumsar branch was recently directed to refund Rs5,00,250 with 9% annual interest from July 18, 2021, after Nagpur District Consumer Disputes Redressal Commission held that the bank failed to take necessary precautionary measures even after receiving a timely complaint about fraudulent transactions.
A bench comprising president Sachin Shimpi and members Balkrishna Chaudhari and Sheetal Petkar also ordered the banking behemoth to pay Rs30,000 towards compensation and litigation costs. He also lodged a complaint on govt’s cybercrime portal on July 19, 2021. As per the complainant, he immediately informed SBI about the fraudulent transactions, got his bank account and debit card blocked and approached the police.
It also noted that the complainant had informed the bank within 24 hours, provided details of the debited amounts and sought reversal of the fraudulent transactions. The commission held that the bank had failed to take necessary steps after receiving the complaint and was thus involved in deficiency of services under Consumer Protection Act, 2019. Because he had shared the OTP, sBI denied liability and contended that Meshram was responsible for the transactions.
You Can Also Check: Gold Rate in Nagpur | Silver Rate in Nagpur | Bank Holidays in Nagpur | Public Holidays in Nagpur | Petrol Price in Nagpur | Diesel Price in Nagpur | CNG Price in Nagpur | LPG Price in Nagpur Stay updated with the latest Nagpur news. The bank pointed out that he had been negligent while handling the transaction. The commission rejected the defence, observing that the circumstances indicated that the OTP and other information were not intentionally shared by Meshram but had been fraudulently obtained by a third person. Download the TOI App.
The case concerned complainant Vindhyan Meshram, who contacted a customer care number on July 18, 2021, regarding a defective product purchased online. The complainant later discovered that Rs5,00,250 had been withdrawn from his account through 13 transactions, with various online payment gateways shown as beneficiaries. He subsequently received a call from a person claiming to facilitate a refund. Acting on the caller’s instructions, the complainant installed an application on his mobile phone. Meshram, through counsel Mahendra Limaye, contended that the bank failed to conduct an internal investigation, monitor the transactions or take steps to stop the fraudulent transfers despite being informed promptly. He also alleged deficiencies in transaction monitoring and velocity-check mechanisms. Limaye further argued that instead of tracing the source of the fraudulent transactions and the beneficiaries, the bank blamed the customer and sought to avoid responsibility.