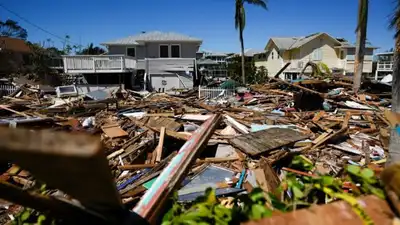
In an opinion issued on October 16, Florida’s Sixth District Court of Appeal ruled that two Lee County homeowners could not force the insurer to pay their legal bills under the confession of judgment rule. Citizens Property Insurance Corporation, involved a home damaged by Hurricane Ian in October 2022. A Florida appeals court has rejected a claim for legal fees and interest filed by homeowners against state-backed Citizens Property Insurance Corporation. The dispute followed disagreements over repairs for storm damage caused by Hurricane Ian. The homeowners had filed a lawsuit while an out-of-court appraisal was still underway, in what the court described as a “race to the courthouse. The case, Susan Reed and Kent Lonngren v. The court found that Citizens had met all its obligations under the insurance policy and paid the final binding appraisal award within the deadline set by the contract.
Reed and Lonngren reported structural damage and water damage to their home on October 4, 2022, shortly after Hurricane Ian made landfall in southwest Florida, according to court filings published by Justia Law. Citizens accepted the claim and initially paid $11,101.19. The estimate totalled $157,727.00. The final interim payment was sent on June 1, 2023. On September 26, 2023, before the appraisal was finished, Reed and Lonngren filed a breach of contract lawsuit against Citizens in the Circuit Court for Lee County. They claimed that Citizens had failed to complete the appraisal within the 90-day period mentioned in Florida’s statutory guidelines. Citizens paid the full amount within the 60-day deadline required by the insurance contract.
Citizens reported that the homeowners’ appraiser refused to accept any candidates other than those he had personally suggested. The homeowners later submitted a repair estimate prepared by their own independent contractor. Eight days later, the homeowners filed a formal notice stating that they intended to start a lawsuit. Citizens responded by using the policy’s mandatory appraisal clause to settle the disagreement over the value of the damage. Under Florida property insurance policies, the appraisal process requires each side to choose an independent appraiser. The two appraisers then review the damage and select a neutral umpire to settle any disagreements that remain. Both sides appointed their own appraisers, but they could not agree on an umpire. Citizens asked the court to pause the lawsuit and require the parties to finish the appraisal process. Circuit Judge Kyle Cohen approved the request. He directed both sides to agree on an umpire or allow the court to appoint one. After the parties agreed on an umpire, an appraisal award was issued in favour of the homeowners.
Over the following months, Citizens inspected the property again, reissued earlier payments at the policyholders’ request, and made additional payments.
The homeowners appealed the decision to the Sixth District Court of Appeal under docket number 6D2025-0917. The judges clarified that Florida law allows policyholders to file a lawsuit if an appraisal remains incomplete after 90 days.
They said this entitled them to interest for the period before judgment and reimbursement of their legal fees. “In this case, there was no breakdown in the claims adjusting process, and Appellants’ lawsuit was not a necessary catalyst to resolve the dispute,” Judge Stargel wrote in the opinion published by Justia Law. After Citizens paid the award, both sides filed motions asking the trial court to rule in their favour without a full trial. Reed and Lonngren argued that Citizens’ payment of the higher appraisal amount amounted to a legal “confession of judgment. Judge Cohen ruled in favour of Citizens, finding that the insurer had followed the policy and had not broken the contract. Writing for the unanimous three-judge appeals panel, Judge Meredith L. Stargel upheld the lower court’s decision. She explained that the confession of judgment rule does not apply when an insurer acts in good faith and follows the claims process agreed to in the insurance contract. “The record demonstrates that Citizens quickly accepted coverage and issued payment, conducted an additional investigation, issued additional payments, promptly demanded appraisal upon receiving the notice of intent, and timely paid the resulting award. The appeals panel also addressed the homeowners’ argument about legal deadlines. However, that rule does not set an absolute deadline for completing the appraisal itself. Judges Jared E. Mize and John K. Gannam agreed with Judge Stargel’s opinion. Their decision left the lower court’s ruling in favour of Citizens Property Insurance Corporation unchanged.