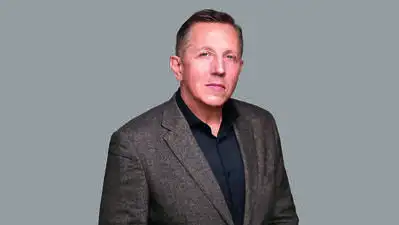
Ben Backwell, CEO, Global Wind Energy Council
In 2025, the global wind power sector added more than 160GW of capacity to the grid, accounting for roughly a quarter of total renewable energy capacity additions. Around 133 countries are now adopting wind power as their preferred source of energy, with much of the growth coming from emerging economies, including India. Ben Backwell, CEO, Global Wind Energy Council (GWEC), the trade body representing the industry, was recently in Chennai. In an interview, he spoke about India’s potential, TN’s opportunities, hybrid energy systems and repowering. Edited excerpts:
What is the outlook for the global and Indian wind industry in 2026? The global wind industry had its best year in 2025, with 178GW of turbines installed, of which around 165GW was connected to the grid. India added 6.3GW, an improvement after several years of annual additions below 5GW. We expect some moderation in 2026 as China adjusts to market changes after installing more than 120GW in 2025. Europe could add 24GW, against 19GW last year, while India could reach 7.5GW. Global installations may be in the high 150GW range, with growth resuming in 2027. India has utilised only around 5% of its technical wind potential, leaving room for expansion. Moving from 6.3GW to 7.5GW would be a step in the right direction.
You Can Also Check: Gold Rate in Chennai | Silver Rate in Chennai | Bank Holidays in Chennai | Public Holidays in Chennai | Chennai AQI | Weather in Chennai | Petrol Price in Chennai | Diesel Price in Chennai | CNG Price in Chennai | LPG Price in Chennai Stay updated with the latest Chennai news. China drove much of the growth, while other markets also performed well. However, installations could still reach around 100GW, which is emerging as the new normal. What is driving improvement in India’s market? Better project execution, favourable prices and changing market dynamics are helping. The industry is moving beyond individual turbines towards integrated solutions combining wind, solar and battery storage. Standalone solar can increase overall system costs. Combining wind, solar and batteries can provide a more efficient and cost-effective energy system, depending on local resources. Our ambition is for India to reach at least 10GW of annual installations, potentially rising to 12GW, 13GW or even 15GW. Is the shift towards hybrid projects creating new opportunities for wind? Absolutely. Relying on standalone solar may not always deliver the lowest overall system cost. Where wind resources are strong, combining wind with solar and batteries can be more economical. Where wind resources are weaker, solar with battery storage may make more sense. The aim is to generate electricity at the lowest possible cost while maximising use of existing grid connections. Combining wind and solar can improve utilisation of transmission infra as the two sources can generate electricity at different times. Hybridisation offers opportunities in India, where wind potential remains largely untapped. Is the current policy framework adequate to accelerate wind capacity addition in India? The central govt has been supportive, setting targets and demonstrating a strong commitment to renewable energy. The bigger constraints are at the implementation level, particularly in the states. Projects awarded through central auctions must be implemented with state agencies, which may lack the capacity or willingness to accommodate projects at that scale. Grid coordination and planning are also challenges. These are not uniquely Indian problems. The European Union has supportive regulations, but implementation varies across member states. Better coordination with state govts is essential. There is scope to accelerate execution. What should TN do to regain momentum in the wind sector? The state govt needs to be more proactive. The new govt has many first-time legislators who will need time to understand the industry. Officials must engage actively with industry, particularly as neighbouring states compete aggressively for investments. TN has natural advantages, including an established wind energy supply chain, excellent ports and a strong industrial ecosystem. These could help the state emerge as a wind manufacturing hub. A clear policy framework and more effective implementation can give the sector the necessary push. What are challenges in repowering India’s ageing wind turbines? Repowering has considerable potential, but implementation is complicated. Many early Indian projects involved relatively few turbines, multiple landowners and villages, and several distribution-grid interfaces. The challenge is to repower at scale rather than turbine by turbine. Existing land agreements and contracts must be addressed, while transmission infra, substations and local grids may need upgrades to accommodate higher capacity. Spain has developed a framework allowing existing project approvals to be carried forward, avoiding the need to repeat the entire planning process. Developers can apply to replace turbines, subject to grid approval and confirmation of adequate injection capacity. Capital expenditure incentives also encourage owners to repower rather than continue operating older machines. India could consider a similar approach, starting with projects offering the greatest potential and adequate grid capacity. Larger projects at sites with strong wind resources could be prioritised before tackling smaller, more complicated locations. Download the TOI App.